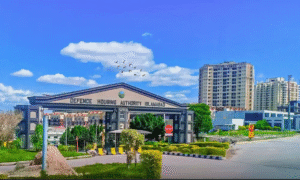
The Supreme Court has rejected DHA Islamabad’s request for income tax exemption, ruling that its development and administrative responsibilities do not automatically qualify it as a local authority.
A three-member bench headed by Chief Justice Yahya Afridi, with Justice Naeem Akhtar Afghan and Justice Muhammad Shafi Siddiqui, decided the appeals filed by DHA Islamabad under the Income Tax Ordinance, 2001. Justice Siddiqui wrote the judgment.
The court said an institution must have specific legal powers to qualify as a local authority for tax purposes. These include the authority to impose taxes, rates or duties and the ability to control and maintain its own local or municipal funds.
The judges found that DHA Islamabad had not demonstrated that it possessed these powers. Its responsibilities for developing and managing its area were not enough to give it the legal status of a local authority.
The court also considered whether the authority’s financial arrangements could support its claim for the exemption. It concluded that DHA Islamabad had not established the required legal control over a separate local fund.
The judgment distinguished DHA Islamabad from the Thal Development Authority, which had previously been recognized as a local authority because its governing law gave it wider powers, including the ability to impose taxes and maintain its own funds.
The Supreme Court consequently dismissed DHA Islamabad’s appeals and held that it does not qualify as a local authority under the relevant provisions of the Income Tax Ordinance.
This means DHA Islamabad cannot claim the income tax exemption available under Section 49(2) on the basis that it qualifies as a local authority.