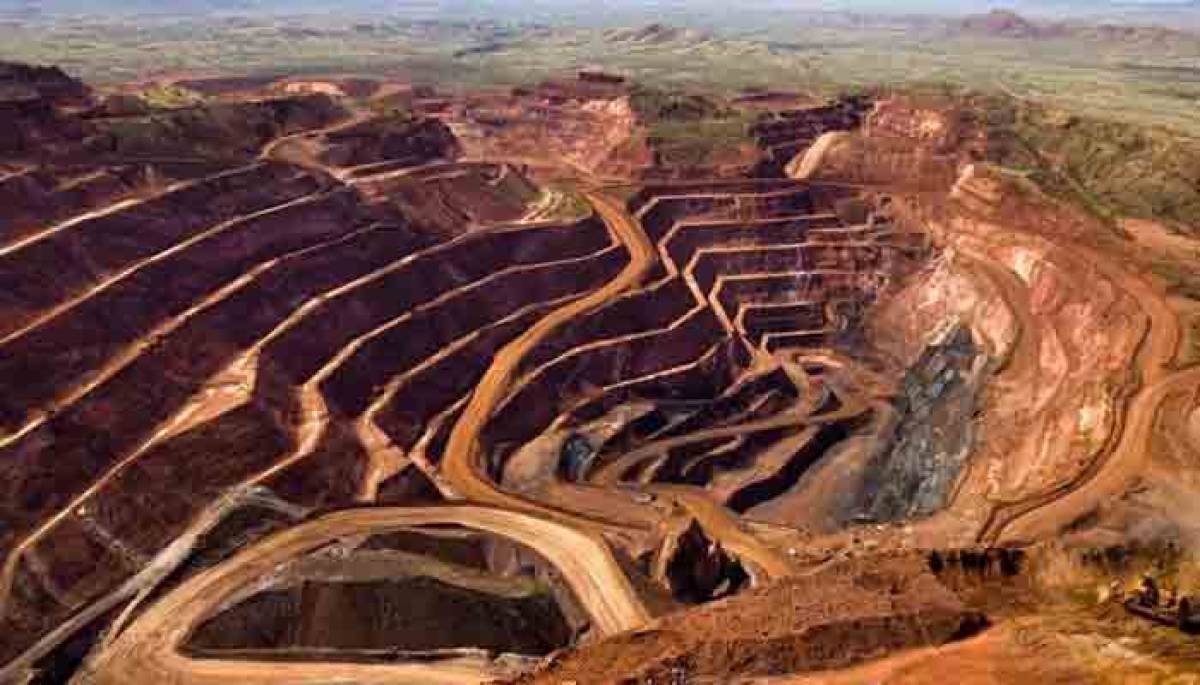
The government is considering a 30-year tax relief package to attract foreign investment in Pakistan’s copper and gold mining sector, with the country’s mineral reserves estimated at $8 trillion.
The proposed incentives include long-term tax exemptions, reduced withholding taxes, import duty relief and deferred tax payments under the National Mineral Policy 2026. The package has been developed using a fiscal model prepared by consultancy Wood Mackenzie.
The government plans to present the proposed incentives to international investors at the Pakistan Minerals Investment Forum (PMIF), scheduled for November 12 and 13. However, the package still requires approval from the Finance Division, which has been asked by the Petroleum Division to expedite the process.
The proposals were initially submitted to the Finance Division during this year’s budget preparations, but a comprehensive incentive package was not introduced. Sources said the National Mineral Policy was ready, but the lack of supporting fiscal incentives could weaken efforts to attract investment into the sector.
Proposed Tax Exemptions for Mining Companies
Under the proposed framework, mining companies could receive a 30-year exemption from general sales tax (GST) on imported and locally purchased goods and services used during exploration and development, until commercial production begins.
The government is also considering extending GST relief beyond the production stage, particularly for export-oriented projects where input sales tax cannot be adjusted.
The Wood Mackenzie model also proposes reducing withholding tax on locally purchased goods and services to 4 percent and 8 percent, respectively, with payments deferred until mining operations begin production.
Mining companies could also receive exemptions from customs duties and import taxes on machinery, equipment and other capital goods required during exploration, development and construction.
Govt Considers Replacing Corporate Tax With 1% Levy
One of the major proposals involves replacing conventional corporate income tax with a 1 percent presumptive tax on export proceeds, alongside a 0.5 percent development surcharge.
The proposed arrangement is intended to provide investors with a simpler and more predictable tax structure.
Wood Mackenzie identifies corporate income tax as the biggest fiscal factor affecting the internal rate of return (IRR) for mining investors.
The package also proposes a 30-year exemption from super tax and a 15-year withholding tax exemption on dividends distributed after commercial production begins.
Inter-company dividends within mining project structures could also be exempted to prevent multiple layers of taxation.
Tax Protection for Mining Investors
The proposed framework includes fiscal stability provisions to protect the tax conditions applicable when mining companies receive exploration concessions or sign project agreements.
The arrangement would broadly follow the protections already available to investors in Pakistan’s oil and gas sector.
Wood Mackenzie considers these protections important because mining projects often require several years of exploration and development before generating revenue. Investors therefore need certainty about the tax rules that will apply throughout the project lifecycle.
The proposed framework also seeks to bring mining projects closer to the special fiscal regime available to the oil and gas industry under the Fifth Schedule of the Income Tax Ordinance, 2001.
Mining Companies May Get Major Depreciation Relief
The proposed incentives also cover exploration losses and depreciation allowances.
Mining companies could be allowed to carry forward exploration losses indefinitely, recognizing that exploration expenses may accumulate years before a project starts commercial production.
The framework also proposes allowing losses from unsuccessful exploration projects to be adjusted against profitable mining projects within the same corporate group, subject to safeguards.
In addition, companies could receive a 10-year period to carry forward depreciation allowances after commercial production begins.
The Wood Mackenzie model proposes accelerated depreciation of up to 100 percent, including doubling the standard depreciation rate from 15 percent to 30 percent.
The proposed measures are aimed at reducing the financial risks associated with long-term mining investments and making Pakistan’s mineral sector more competitive for international investors.